Showing posts with label Newswire. Show all posts

11/02/2026

Omen Bought the Other Half of the Sensor It Sells to Data Centers

SeaPRwire – Omen AI will pay $16 million in cash and stock for Aquatic Labs, a competitor that had been building its own real-time sensor for the water running through data center cooling loops. The company confirmed the deal on Monday.

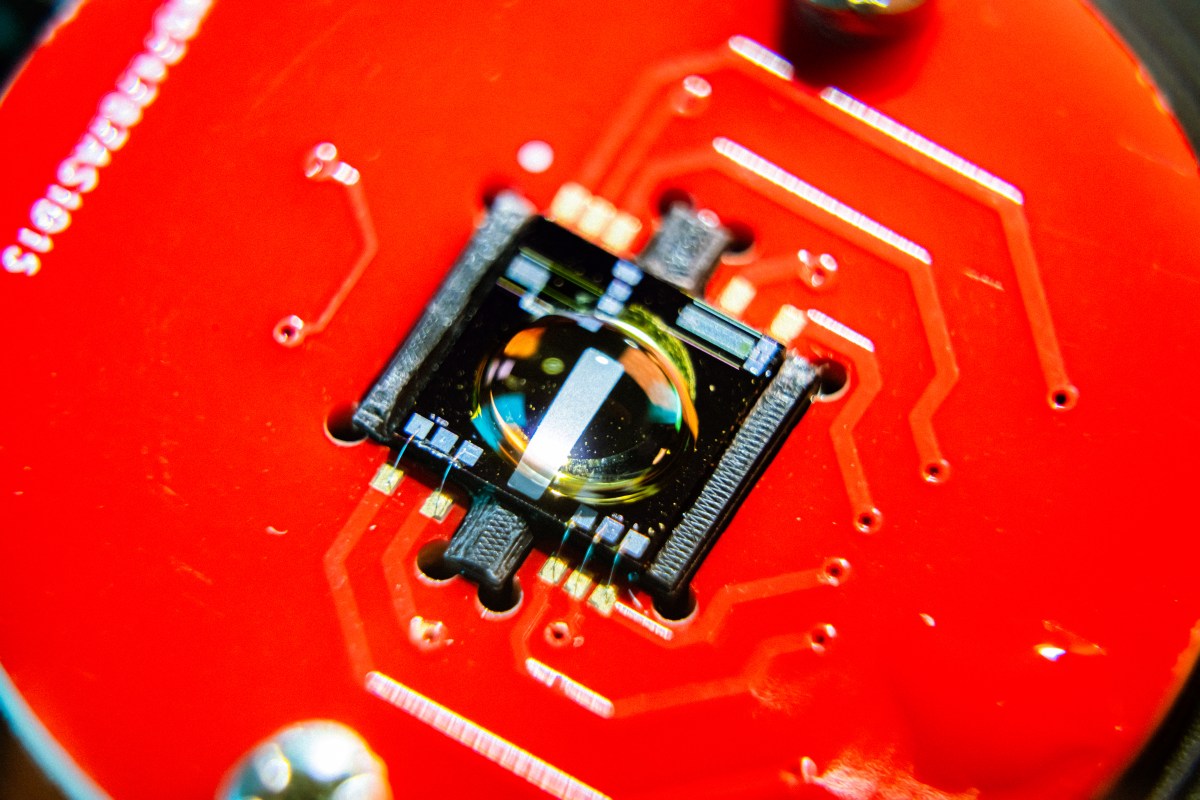
The two products measure different things. Omen’s sensor looks for elements dissolved in the fluid; Aquatic Labs’ looks at alkalinity. Putting both into one housing is supposed to give operators a reading they can act on instead of a number they have to interpret against a lab report that arrives three days later.

The two measurements catch different failures. Corrosion and scale begin in the chemistry of the loop, and biological growth usually announces itself as a pressure drop that nobody reads until a heat exchanger is already fouled. A probe that reports both also cuts the number of sampling kits a facilities team keeps on site, which is the operational argument for consolidation. It is not an argument that either metric is better than the other.

Cooling fluid is where a lot of money quietly disappears. When a valve starts to fail or bacteria take hold in a loop, the cheaper response is usually to dump the water and refill rather than risk fouling the equipment it protects. That means stopping work on racks worth more than the water ever was. Keeping the same fluid in service longer is the entire commercial case for monitoring it continuously, and it is a case Omen has been making since it raised a $31 million Series A in June (techcrunch.com/2026/06/29/omen-ais-plan-to-optimize-data-centers-is-all-wet/).

The founders arrived from opposite directions. Zach Laberge left high school to start a company that ran fluid analysis for construction machinery dependent on hydraulics. Allan Adams spent most of his career as a physicist building ocean sensing instruments at MIT and the Woods Hole Oceanographic Institution before founding Aquatic Labs. Adams is now Omen’s chief science officer; Laberge runs the company.

Their integration target is a single sensor, expected on the market early next year. Omen says its current units will be monitoring chips drawing 250 to 300 megawatts of power by the end of 2026, a slice of installed capacity Laberge puts at roughly $5 to $7 billion, with a goal of covering the equivalent of a gigawatt by the end of 2027.

Put those numbers against the water itself. Data centers in the United States use 17 to 19 billion gallons a year for cooling, according to The Water Foundation, and that figure is expected to triple within five years. A monitoring product that reduces how often a facility drains and refills its loops touches both the water bill and the discharge permit, which is why Adams frames the municipal end of the pipe as part of the same problem: fluid leaves the building and enters a public system, and someone has to be able to show what is in it.

The demand side has become noisier. Companies once floated as much as $4 trillion in AI infrastructure spending by 2030 (techcrunch.com/2026/02/28/billion-dollar-infrastructure-deals-ai-boom-data-centers-openai-oracle-nvidia-microsoft-google-meta/), and investors have spent recent weeks marking down the companies paying for it (techcrunch.com/2026/10/30/cracks-are-emerging-in-the-ai-spending-boom/). Omen’s answer is that its customers are not the ones deciding whether to build. “We’re working [with] customers on stuff they’re building today or have already built, and so it doesn’t really affect us because all of those projects were financed 12 months ago,” Laberge said. “Our view is, if there’s tightness, this is still going to be the biggest market in human history, even if you sliced it in half.”

That argument holds for the next several quarters and gets weaker after that. A sensor installed in a plant that broke ground in 2025 is revenue no matter what happens to construction starts in 2027. A pipeline that depends on new plants does not have that protection, and the company has not said how much of its booked business runs past the current build cycle.

The deal also thins out the supply side. Operators weighing continuous water monitoring have had at least two small vendors to compare against each other; after this acquisition, one of them belongs to the other. Nothing in the announcement says whether existing Aquatic Labs customers keep their contracts and their sensor firmware on the same terms.

The engineering claim needs the same kind of scrutiny. Merging an ion sensor and an alkalinity sensor into one package is a materials problem as much as a software one: the two measurements want different conditions, and a combined probe has to hold calibration across the water chemistries used in different climates and different cooling designs. Omen has not published field data showing drift rates for the combined unit.

The combined unit does not exist yet.

Adams describes the result as a much richer picture of the water and the fluid. Richer is not the same as validated: the company has published no comparison of its readings against laboratory results, which is the standard the permits currently rest on.

There is also a question of who the buyer becomes. Data center operators buy uptime. Water utilities buy compliance, on annual budget cycles, through procurement processes that treat new instrumentation as a capital item to be piloted for a year. Adams wants the same sensors measuring discharge into municipal systems, which is a reasonable extension of the technology and a much slower sales motion than the one Omen has been running with hyperscale tenants.

What the deal actually buys, then, is a competitor’s chemistry expertise and a founder who can talk to scientists, paid for partly in stock. Sixteen million dollars is small against the cost of a single loop shutdown at a large campus, which is the comparison Omen would like operators to make. It is also small enough that the company will need another round before the combined sensor has a track record.

Two things are checkable from here. Whether the integrated unit ships on the timeline the company gave, and whether operators will accept continuous readings in place of the lab samples their permits and maintenance contracts currently specify. The second is the harder one, and no sensor specification answers it.


source https://newsroom.seaprwire.com/press-releases/technologies/omen-bought-the-other-half-of-the-sensor-it-sells-to-data-centers/

COP17 Closed With a Roadmap, $2 Billion, and Four Years Left

SeaPRwire – COP17 closed in Yerevan on Saturday with a document called the Yerevan Pathway, about $2 billion in new funding pledges, and four years left to deliver 23 biodiversity targets that a global review has already found the world is not on track to meet.

The gap between those two facts is the story. A conference that ends with nearly 50 decisions and a named pathway has produced the machinery of a plan, not the outcomes the plan exists to produce, and the calendar is now shorter than the implementation cycle of most of what was agreed.

What the pathway asks for is specific enough to check. Countries are to phase out subsidies that harm nature, align national budgets and economic decisions with the framework, and increase financial, scientific and technical support to developing countries. It also asks for stronger monitoring and reporting, which is the part with teeth, because a target nobody reports against cannot be judged missed.

The nearly 50 decisions adopted cover protected areas and forests, wildlife management, invasive alien species, marine and coastal biodiversity, and synthetic biology. Most of them are guidance for national implementation, which means their effect is decided in capitals rather than in Yerevan. A decision that a ministry never reads has the same force as one that was never adopted, and the conference has no way to tell the two apart until reports come in.

The funding announced is real money and modest relative to the problem. Nearly $2 billion was pledged, including $560 million from the Global Environment Facility’s latest replenishment, $500 million through the Species Recovery Alliance, and $330 million for the Value Nature Fund, which is meant to pull in private capital. The Asian Development Bank added a biodiversity bond and an investment incubator. None of the announcements came with a disbursement schedule, and pledges made at a conference are commitments of intent until a finance ministry writes them into a budget line.

The channels matter as much as the totals. The Global Environment Facility is the established multilateral route, with an allocation process and recipient governments on the other end. The Species Recovery Alliance and the Value Nature Fund are newer vehicles, and the second is explicitly designed to raise money from private investors. When a conference reports a single total, it blends money that will be programmed by agencies with money that has to be raised from asset managers first. Neither the alliance nor the fund published a project pipeline in Yerevan, so both remain announcements until projects are named.

Finance is the demand that recurs at every one of these meetings, and the pathway answers it the way previous outcomes did: by calling for more support to developing countries without attaching an amount or a schedule to the call. The countries asking have argued for years that they cannot align budgets with a framework whose targets assume money they do not have. Nothing adopted in Yerevan settles that.

Two institutional changes will outlast the headline number. The Sevan Guidelines set the operating rules for a new permanent body that gives Indigenous Peoples and local communities a formal role in shaping global biodiversity policy, which converts a consultation habit into a standing seat. Separately, parties agreed new indicators for monitoring and accountability. Indicators sound administrative.

They are how a voluntary framework becomes falsifiable: with agreed metrics, a country’s failure shows up in a table rather than in an argument.

The 23 targets were adopted in 2022 under the Kunming-Montreal framework, and the review that preceded this conference concluded that the world is off track on them. That finding was not disputed in Yerevan. The dispute was over who pays and who reports, which is why the finance language and the subsidy language carry more weight than the number of decisions adopted.

What that review can see is worth separating from what it cannot. National reports describe policies and programmes; they do not measure whether an ecosystem recovered. A country can record a subsidy reform and new protected areas without either changing the trend line the review tracks. Asking governments to align budgets with the framework is an attempt to move the measurement from intentions to money, which is why that clause carries more operational weight than the rest of the pathway.

Nothing in the outcome creates an enforcement step.

The pathway calls on governments; it does not oblige them, and the mechanism for a country that ignores it remains reputational. Astrid Schomaker, the convention’s executive secretary, put the test where it belongs: not what governments agreed in Yerevan, but what they change when they return home. That is an accurate description of how this process works and also an admission of where its leverage ends.

The $2 billion should be read against that structure. Private capital vehicles like the Value Nature Fund and the ADB’s bond are attempts to move money that governments will not appropriate, and they come with the usual condition: investors need a return, which means projects that generate revenue, which is a narrower set than the ecosystems under pressure.

What Yerevan did do is set up the next measurement point. COP18 meets in Ecuador with two years left on the targets, which makes the national reports filed between now and then the only place where the pathway can be tested. Ecuador also inherits the new body’s first budget and the first round of reporting against the agreed indicators, an agenda that assumes the machinery works before anyone has run it. If the subsidy commitments appear in budgets, the process has moved. If the reports arrive late or partial, the four years will pass the way the last four did.

Hambardzum Matevosyan, who presided over the conference, described two weeks in which differences were bridged and commitments became decisions. Inger Andersen of UNEP said environmental multilateralism had prevailed again. Both statements are true of the room. Whether they are true of the decade depends on a set of documents that will be filed by finance and environment ministries, in national capitals, with no conference president in the chair.


source https://newsroom.seaprwire.com/press-releases/political/cop17-closed-with-a-roadmap-2-billion-and-four-years-left/

11/01/2026

Mexico Is Ageing on an Income It Cannot Retire On, and the Budget Already Shows It

Why a fertility rate of 1.2 and a pension bill above 6% of GDP measure the same problem, and the two indicators that could prove this wrong

AsiaPresswire – Mexico’s fertility rate was 1.9 children per woman in 2019. In 2024 it was 1.2. Replacement is 2.1. In five years the country moved from a fertility profile that roughly holds a population steady to one where each generation is 43% smaller than the one before it, and it did so at a income level where the state has not finished building the systems that older people need.

That is the whole argument, and it can be falsified in two places. Either fertility recovers toward replacement, or the formal labour market expands fast enough to fund the pension promises already written. If neither happens by 2028, the arithmetic below is not a forecast, it is a schedule.

The Number That Turned

The 2025 inter-census survey, reported by INEGI and relayed through Mexican statistical coverage in 2025-26, put the population at 130.4 million with 19.2 million people aged 60 or over. That is 14.7%. The median age is 32. The ageing index, which counts people aged 60 and over per 100 children aged 0 to 14, reached 68.2, against 47.7 in 2020. Life expectancy at birth is 75.5 years.

None of those numbers is unusual for a middle-income country in isolation. What is unusual is the speed and the sequencing. A fertility rate that falls 37% in five years is not a slow demographic drift; it is a behavioural break, and it arrives before the institutions that amortise it.

Table 1: Six demography indicators, and what each one implies

Indicator Value Year What it changes
Total population 130.4 million 2025 Denominator for every per-capita claim
Population aged 60 and over 19.2 million 2025 14.7% of the total
Median age 32 years 2025 Labour supply still growing, briefly
Ageing index 68.2 per 100 children 2025 Was 47.7 in 2020
Fertility rate 1.2 children per woman 2024 Was 1.9 in 2019
Life expectancy at birth 75.5 years 2025 Duration of the payout

Read the median age and the fertility rate together and the trap appears. A median age of 32 means Mexico still has a large working-age cohort, which is why the fiscal problem does not feel urgent in 2026. A fertility rate of 1.2 means that cohort is the last large one. The two facts are consistent, and they point in opposite directions for about fifteen years.

Three Variables, Not One

Most commentary on Mexican ageing collapses into a single variable, usually the dependency ratio, and then argues about projections. The dependency ratio is a consequence. Three variables drive it, and only three matter for the next decade.

Fertility. At 1.2, Mexico is below every OECD member except Korea and Italy, and it got there faster than either. Fertility is the slowest variable to reverse and the fastest to move; it responds to housing costs, female labour participation and contraceptive access, none of which a pension reform touches.

The contributory and non-contributory split. Mexico runs two pension systems that behave in opposite ways. Contributory pensions, financed by worker and employer contributions through IMSS and ISSSTE, are contractually fixed and growing with the number of retirees. Non-contributory transfers, financed from the budget, are discretionary and politically expandable. In 2026 the budget froze the first and expanded the second, and that is the decision that matters.

Coverage. The share of the population covered by public health insurance fell from 77.1% in 2020 to 72.5% in 2025. Coverage is the variable that determines whether an ageing population shows up as fiscal cost or as household cost. When coverage falls while the old population grows, the cost does not disappear. It moves to the family, and then to the private clinic.

What the 2026 Budget Actually Did

The 2026 expenditure budget allocates 2.3 trillion pesos to pensions, an increase of 3.7% overall. That headline number hides the structure.

Contributory pensions, the ones that depend on contributions from workers, employers and the state, rise by 0.05%. The IMSS pension budget falls 2.5%. The ISSSTE budget falls 2.3%. The number of pensioners grows about 3% a year. Meanwhile the non-contributory old-age pension rises 5.2%, the disability pension 20.8%, and the new pension for women aged 60 to 64 rises 266%, expanding to three million beneficiaries.

Table 2: The 2026 pension budget, by line

Line 2026 change Beneficiaries Political status
Total pension spending +3.7% — 2.3 trillion pesos
Contributory pensions +0.05% about 3% more each year Contractual
IMSS pension budget -2.5% largest block of retirees Contractual
ISSSTE pension budget -2.3% public-sector retirees Contractual
Old-age pension, 65 and over +5.2% 13.7 million Discretionary
Disability pension +20.8% 2.0 million Discretionary
Pension for women aged 60-64 +266% 2.8 million registered Discretionary
Total social programme beneficiaries — 42.8 million —

Two things follow, and they are not ideological.

First, the contributory system is being asked to deliver a 3% larger caseload on a budget that grows by five hundredths of one percent. That is arithmetically a cut in the real value of each pension, before inflation. Divide 1.0005 by 1.03 and the real value per beneficiary falls 2.9%. Add 4% inflation and the fall is 6.6% in a single year.

Second, the non-contributory system is becoming the larger growth engine. Thirteen point seven million people receive 6,400 pesos every two months, which is 3,200 pesos a month, about US$171 at 18.7 pesos to the dollar. The women’s pension pays 3,100 pesos every two months, 1,550 a month, about US$83. Multiply by beneficiaries and the two transfers cost roughly 578 billion pesos a year, or 25% of the entire pension budget.

That 25% is the number to hold onto. A quarter of Mexico’s pension money now moves through programmes that a future government can change with a budget line, and three quarters moves through contracts that a future government cannot. The fiscal risk is not that pensions are too generous. It is that the rigid part is frozen while the flexible part expands, and the flexible part is the one that reaches the poorest old people.

The Arithmetic of a Frozen Line

Here is where an ageing population becomes a budget problem rather than a demographic one.

The pension bill passed 6% of GDP in the 2026 budget and approaches a quarter of net public spending, according to the Centre for Economic and Budgetary Research. Six percent of GDP is not remarkable against the OECD, whose public pension spending sits in the region of 8%. What is remarkable is the ratio to the old-age share.

Divide 6% by 14.7% and Mexico spends about 0.41 percentage points of GDP for every percentage point of population aged 60 and over. Do the same for an OECD average of roughly 8% of GDP and roughly 24% of population aged 65 and over, and the figure is 0.33. Mexico is spending about a quarter more per old person, relative to its output, than the rich-country average.

The comparison has an obvious flaw and it runs in one direction. Mexico’s 14.7% counts people aged 60 and over, while the OECD’s 24% counts 65 and over. Using the higher threshold for Mexico would shrink the denominator and raise the ratio further, so the flaw makes Mexico look cheaper than it is, not more expensive. The conclusion survives the correction.

Table 3: Pension spending against old-age share

Measure Mexico, 2026 OECD reference Ratio
Public pension spending, % of GDP 6.0 about 8.0 0.75
Population above the threshold, % 14.7 (60+) about 24 (65+) 0.61
Spending per point of old-age share 0.41 0.33 1.23
Share of net public spending about 25% — —

A country that spends like a rich country on pensions while collecting taxes like a middle-income one has three options, and it is worth naming them plainly because every Mexican budget since 2020 has chosen among them implicitly.

  • Raise contributions or taxes, which hits the formal sector that is already paying.
  • Cut the real value of contributory pensions, which is what a 0.05% increase against 3% more pensioners does by default.
  • Expand non-contributory transfers and accept that the fiscal cost grows with the elderly population rather than with the wage bill.

The 2026 budget chose the second and the third at the same time. That is a coherent political strategy and an incoherent fiscal one, because the two choices have different growth rates.

The ratio has a clock on it, and the clock is easy to read. If the number of pensioners grows 3% a year while the number of registered workers grows 1%, the ratio of contributors to retirees falls 1.9% a year, and 17.8% over a decade. That is not a crisis scenario; it is the current trend extended. To hold the ratio flat, registered employment has to grow at the same 3% as the pensioner count, which in a country where informal work still accounts for a majority of employment is a labour-formalisation target rather than a growth target. Framed that way, the pension debate and the informality debate are one debate, and the 2026 budget treated them as two.

Who Is Hit First: Women Aged 60 to 64

The distributional answer is unusually clear, and it comes from the design of the new programme rather than from advocacy.

A woman who turns 60 in Mexico in 2026 and who spent her working life in the informal economy has no contributory pension, because she never had an employer contributing on her behalf. She becomes eligible for the women’s pension at 60, four years before the universal old-age pension at 65, and she receives 1,550 pesos a month, about US$83.

Two point eight million women are registered. The budget for that line rose 266% in one year, which is the largest percentage increase in the entire pension bill and the clearest statement of political priority in the 2026 budget. It is also a recognition of a real gap: Mexican women have lower formal labour participation, more interrupted contribution histories, and a longer life expectancy than men, which means they draw a smaller pension for more years.

The programme is means-tested by age and gender, not by contribution history, so it reaches exactly the group the contributory system never covered. That is its strength. Its weakness is that 1,550 pesos a month is not a pension. It is a transfer that covers part of a household’s food bill, and it will be paid for as long as the budget line exists.

The second cohort is less visible. Workers hired before July 1997 fall under the 1973 pension law, which calculates the benefit from the average salary of the last five years rather than from an individual account. That group had a legal route to raise its own pension by making voluntary contributions at a higher declared salary, known as Modalidad 40.

On 22 October 2026 that route narrowed. New entrants can only contribute on the last salary registered with the institute plus one unit of measurement, with the UMA set at 117.31 pesos a day for 2026. Retroactive payments from before the application date are no longer possible, and self-employed workers registered under Modalidad 10 cannot also take Modalidad 40. For a worker who was planning to spend five years raising his declared salary before retiring, the option closed on a specific date, and the difference between the pension he expected and the one he will receive is not a projection. It is a subtraction.

Two Indicators That Are Actually Independent

Forecasts about ageing are cheap. What is expensive is knowing which number to watch, and the two numbers below are chosen because they move for different reasons.

The first is the ratio of IMSS-registered workers to the population aged 60 and over. This is the contributory base divided by the people it must support, and it is published monthly. If the ratio rises, formal employment is outrunning ageing and the contributory system can hold. If it falls, every promise in the 1973 and 1997 laws becomes a claim on general revenue.

The second is private spending on geriatric care. IMARC put Mexico’s geriatric healthcare market at US$20.58 billion in 2025. This indicator measures the cost that has already been pushed out of the public system into households. It is independent of the first because it responds to coverage, not to employment: when public health coverage falls from 77.1% to 72.5%, the private market grows whether or not more people have formal jobs.

Table 4: The two indicators, and what each one is measuring

Indicator Source Frequency What a move means
IMSS-registered workers per person aged 60+ IMSS Monthly Contributory solvency
Private geriatric care spending IMARC and clinic filings Annual Cost shifted to households
Public health coverage share INEGI Annual Whether the shift accelerates
Ageing index INEGI Annual Speed of the demographic turn

Watch the first two together. If registered workers per old person is stable and private geriatric spending is growing at double digits, Mexico is not facing a pension crisis; it is facing a care crisis, and the money is already leaving households to pay for it. If both deteriorate, the pension problem and the care problem arrive in the same fiscal year, which is the scenario that the 2026 budget’s structure makes likely.

What Would Prove This Wrong

Three observations would break the argument, and each is measurable within two years.

  • Fertility recovers above 1.6. A rebound of that size would require either a large-scale childcare expansion or a change in housing costs that no current policy implies. If it happens, the 2045 dependency ratio is materially better than the schedule above.
  • Formal employment grows faster than the old population for three consecutive years. IMSS registrations have grown in most years since 2010, but rarely faster than 3% net. Three years above 5% would mean the contributory base is winning.
  • Remittances to households headed by someone over 65 rise sharply. Mexico received record remittances through the 2020s. If those flows are increasingly directed at elderly households, the household sector is absorbing the coverage gap and the fiscal crisis is deferred, not solved.

Put a number on the second observation. Registered employment growing 5% a year against a pensioner count growing 3% raises the contributor-to-retiree ratio 19.4% over ten years, which is enough to carry the 1973 cohort through its peak drawdown without a real cut. That is the size of the move required, and it is why the formalisation rate rather than the fertility rate is the variable to argue about in the next two budgets.

Two of the three are about the labour market, which is the variable that Mexican pension debates consistently underweight. The demographic schedule is set. What is not set is how many people are paying into the system while the schedule unfolds.

Data Basis, Two Limits, and the Number I Could Not Find

The demographic figures come from INEGI’s 2025 inter-census survey as reported in Mexican statistical coverage, and the ageing index comparison uses the 2020 census as the base.

  • Population 130,392,389, aged 60 and over 19,204,670, median age 32, ageing index 68.2, life expectancy 75.5 and public health coverage 72.5% are 2025 INEGI figures, with the 2020 comparators of 47.7 for the ageing index and 77.1% for coverage stated in the same releases.
  • Fertility of 1.2 in 2024 against 1.9 in 2019 is INEGI data reported through Mexico News Daily.
  • The 2.3 trillion peso pension total, the 3.7% overall increase, the 0.05% contributory increase, the 2.5% and 2.3% cuts to IMSS and ISSSTE, and the 6% of GDP and quarter-of-net-spending ratios are from the Centre for Economic and Budgetary Research’s analysis of the 2026 expenditure budget.
  • The 13.7 million old-age beneficiaries at 6,400 pesos bimonthly, the 2.8 million women registered at 3,100 pesos bimonthly, the 266% increase and the 42.8 million total social programme beneficiaries are from the Welfare Ministry’s 2026 briefing.
  • The Modalidad 40 changes, the one-UMA limit and the 117.31 peso daily UMA for 2026 are from the IMSS decree of 21 October 2026 as reported by El Pais on 22 October 2026.
  • The US$20.58 billion geriatric healthcare market is IMARC Group’s 2025 estimate.

Two limits deserve stating. The first is that INEGI’s 2025 figures come from an inter-census survey rather than a census, so the denominators carry sampling error that the published tables do not fully express; the ageing index in particular is sensitive to the estimate of the 0-14 population, which is the hardest group to count. The second is that the OECD comparator uses a 65-and-over threshold against Mexico’s 60-and-over, which I have flagged rather than corrected, because correcting it properly requires age-specific spending data that neither the OECD nor the Mexican finance ministry publishes at that granularity.

One number I could not find is the one that would settle the care question: the share of Mexican households with at least one member over 65 that report out-of-pocket health spending above 30% of household income. The national health and nutrition survey collects the components but not in a form that is published annually at that threshold. Until it is, the private geriatric market size is the best available proxy, and a market size is a weaker instrument than a household survey.

Sources

This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services.

About Global Infinity Labs

Global Infinity Labs is an AI innovation company specializing in MCP data services.

Email: support@globalinfinitylabs.com


source https://newsroom.seaprwire.com/press-releases/finance/mexico-is-ageing-on-an-income-it-cannot-retire-on-and-the-budget-already-shows-it/

10/31/2026

What the Ofcom Information-Notice Ruling Actually Decides, and What It Leaves Open

SeaPRwire – Five grounds went into the Divisional Court. Four of them never reached a hearing on their merits. That procedural detail is the part of the 30 October judgment worth understanding first, because it decides how much of the platforms’ argument was actually tested and how much was simply refused at the gate.

Under the Online Safety Act 2023, section 100 lets Ofcom require regulated services to hand over information the regulator needs to carry out its functions. Meta and WhatsApp, X and TikTok each received notices and each brought judicial review. The judgment, from Lord Justice Singh and Mrs Justice Collins Rice, is reported as [2026] EWHC 2779 (Admin), and it is the first judicial examination of that power.

The four grounds that failed at the permission stage were the argument that the notices circumvented the Act’s separate transparency regime, the argument that the information was not genuinely “required,” the argument that Ofcom had skipped an impact assessment under section 7 of the Communications Act 2003, and, for TikTok alone, predetermination. Permission was refused because the court considered those grounds unarguable, which is a lower bar than being wrong: a ground refused permission does not get argued out in open court, and the reasoning behind the refusal is correspondingly thin.

Proportionality survived that filter. The companies framed it under both section 100(4) and the European Convention on Human Rights, the court granted permission, heard it in full, and rejected it. So of five complaints, exactly one was examined on the evidence, and it lost.

The finding inside that single ground is where the judgment will be cited. The platforms said compliance would impose an extraordinary burden. The court found the evidence offered in support lacked “pertinent substance,” meaning it did not show in concrete terms why the demands were excessive. Read that as a statement about the quality of the record rather than about the size of the burden: the court did not conclude the burden was small, it concluded the platforms had not demonstrated it.

For anyone advising a regulated service on how to resist a section 100 notice, that is the operative paragraph. Expense and complexity are not self-proving. A notice running to hundreds of pages may well cost a great deal to answer; a court will want the costed version, itemised against the specific requests, before it weighs that cost against the regulator’s need. The judgment rewards a company that can produce engineering time estimates, headcount allocations and per-request breakdowns, and penalises one that asserts scale.

What the ruling does not establish is more extensive than what it does. It says nothing about whether the information Ofcom sought was the information it should have sought, only that its decision on that question survives a proportionality review on the record before the court. It says nothing about how Ofcom uses the material, or what standard applies when the data becomes the basis of a breach investigation. Those questions remain where they were.

The transparency argument deserves a note, because it is the one with the widest potential reach. The Act gives Ofcom a separate transparency regime with its own procedures for public reporting, and the companies argued that the information notices were an attempt to route around it. The court found that unarguable. If that conclusion holds through any appeal, the practical effect is that Ofcom can gather material for its own purposes without triggering the disclosure obligations attached to the transparency route, and the two channels stay legally distinct.

Two disputes sit outside this judgment. Meta’s separate challenge to the way fees and penalties are calculated by reference to worldwide revenue is still before the courts, and it addresses a different power: not what Ofcom may ask for, but what it may charge. The platforms may also seek permission to appeal the 30 October decision, which would put the proportionality finding in front of the Court of Appeal and test whether the evidential threshold was set correctly.

The wider read-across is a matter of institutional design rather than of this case. Section 100 is a demand power exercised without prior judicial authorisation. A regulator decides what it needs, issues a notice, and the company either complies or litigates after the fact, which is why the permission stage matters so much: the four grounds that never got heard are the four arguments a regulated service would most want to make. Jurisdictions drafting equivalent regimes will look at how little of the challenge survived, and at how narrow the surviving ground turned out to be.

One asymmetry is worth naming. Because four grounds were refused permission, the court’s reasoning on them exists mainly as a refusal rather than as a reasoned judgment, and a refusal is harder to appeal and harder to rely on in the next case. The proportionality finding rests on a full hearing and a developed record, which makes it the part later litigants can actually use. That is an odd result for a first test of a statutory power: the narrowest ground produced the most durable holding.

What to watch is unglamorous. Whether an appeal is filed. Whether the pending fee challenge produces a different result on a power the court has not yet construed. Whether the data collected under these notices shows up in enforcement action, which is the only test of whether the information was worth demanding. And whether the next company served with a section 100 notice answers it, or spends the effort to build the costed record that this judgment says is required to resist one.

The notice power is not self-executing either. What a platform must produce, in what format and by what date are set by the notice itself, and nothing in this judgment constrains how broadly the next one may be drawn. A ruling that upholds one set of demands says little about the scope of the following set.

The ruling tells regulators their information powers will be enforced and tells companies what kind of evidence it takes to push back. It does not tell anyone whether the requests were well judged, and the court was not asked to answer that.


source https://newsroom.seaprwire.com/press-releases/policy-analysis/what-the-ofcom-information-notice-ruling-actually-decides-and-what-it-leaves-open/

10/30/2026

Mistral Released the Weights and Handed the Safety Burden to Whoever Runs Them

SeaPRwire – A model release is usually a product event. This one is a procurement event. Mistral put the weights for Mistral Large 4, a trillion-parameter model it calls Le Chonk, on Hugging Face and behind its own API on Thursday, which means a customer can now take the checkpoint, install it on hardware it controls, and stop asking permission to use it. The company’s pitch is that this matters most in cybersecurity, where the buyer is a security team that wants to point a model at its own code and its own logs.

Weights are the numerical result of training. Publishing them does not publish the data, the recipe, or the evaluation harness, and it does not oblige Mistral to keep shipping updates. What it does is remove a switch. An API customer’s access depends on a vendor’s continued willingness to serve that customer, at that price, under that policy. A weights customer’s access depends on hardware and electricity. Stock, Mistral’s vice president of science, put the claim in almost exactly those terms: access “can’t be cut off by definition because the model is open-weighted.”

That sentence is the whole strategy, and it is worth being precise about what it guarantees. It guarantees the checkpoint. It does not guarantee a patched checkpoint, a model that improves, or a vendor who answers when something goes wrong at 3 a.m. during an incident. Organisations that adopt open weights for continuity are trading a vendor dependency for an internal maintenance obligation, and the second one is easier to control but harder to staff.

The cybersecurity framing is where the argument gets strongest and least examined. Stock’s case is that closed models ration the work defenders need to do: they rate-limit, and they refuse requests that look like offensive security even when the requester is trying to find a bug in its own systems. A model running on-premises has no provider in the loop to refuse anything. The same property that makes it useful to a defender makes it useful to anyone else, which is the part of the release Mistral addresses with a claim about who benefits first.

“Some malicious actors might try to actually leverage their own technology to attack,” Stock said, arguing that defenders therefore need the capability “as soon as possible.” That is a race argument, not a safety argument, and it has a testable implication: if the defenders who receive the weights are not actually faster than the attackers who can download the same file, the release has moved capability around without changing the balance. Nobody in the announcement offers a way to measure which happened.

Reversal is the other asymmetry. An API can be withdrawn in an afternoon; a checkpoint that has been mirrored cannot be. If a later revision of the model turns out to behave badly on offensive tasks, Mistral can stop shipping it and cannot stop anyone from running the copy already on disk. That is the price of the guarantee Stock is selling, and it is paid by everyone who shares a network with the buyer, not only by the buyer.

The performance claims need the same treatment. Mistral says the model is comparable to the strongest rival open-weight release of recent months and uses 47 percent fewer tokens per task. Token efficiency is not a vanity metric for on-premises buyers; it is the difference between a cluster that fits in a budget and one that does not. But the comparison is Mistral’s own, published with the release, and the 47 percent is an average across whatever task set the company chose.

Separately, Mistral claims the model outranks every other open model on the Coding Agent Index maintained by Artificial Analysis. One index, one vendor-supplied submission, no independent replication in the announcement. It is a real signal — third-party leaderboards are hard to game completely — and it is also a single number standing in for a capability that buyers will experience as a distribution of failures across many repositories.

Mensch’s framing is philosophical: AI should be “a tool for empowerment, not dominance,” and the model reaches “state-of-the-art performance” at “a fraction of the compute and capital committed by closed labs.” The compute claim is the one that would matter most to an investor and the one least verifiable from outside, because nothing in the release states the training budget in a form anyone can check. What can be checked is the download.

There is a quieter commercial logic underneath. A lab that cannot outspend its rivals on training runs can still compete on distribution: if the default self-hosted model for regulated buyers is yours, you sell fine-tuning, support, and the paid tier for everyone who would rather not run a GPU cluster. Mistral’s own statement points at the buyer segment — enterprises and public institutions that want to “download, deploy, and own” the system — rather than at developers who will simply call an API.

That segment has its own constraints. A bank or a ministry deploying a trillion-parameter model on-premises needs the safety behaviour to be somebody’s job. With a closed API, moderation and abuse monitoring sit with the provider by default. With weights, they sit with the operator, who may not have a red team detached to the model and who now owns every refusal decision the model does or does not make. The release shifts capability to the buyer and the responsibility with it, and Mistral’s announcement does not describe what it hands over to help with the second half.

Stock was asked about rogue AI agents and declined to escalate. “We don’t want to fearmonger people. We think it’s a problem that is solvable. It’s a hard problem to have good security.” A lab releasing cyber-capable weights has an obvious interest in that position, and the position is not wrong on its own terms; it is simply not evidence. The evidence would be an evaluation of what the released checkpoint actually does when someone points it at a target without authorization, run by people who do not work for Mistral.

Two things would settle more than the press release does. First, independent red-team results on the released weights, published with methodology, including the refusal rate on offensive tasks rather than a summary adjective. Second, a public account of how many regulated buyers run it in production a year from now and what broke. Until then, the honest description of this release is narrow: a competent lab has made a frontier-scale checkpoint available to anyone who can host it, and has bet that the defenders will be the ones who bother.

This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services.

About Global Infinity Labs

Global Infinity  Labs is an AI innovation company specializing in MCP data services.

Email: support@globalinfinitylabs.com


source https://newsroom.seaprwire.com/press-releases/technologies/mistral-released-the-weights-and-handed-the-safety-burden-to-whoever-runs-them/

10/29/2026

Philippine Tourism Has Three Arrival Counters and a 300,000 Gap

The same eight-month task, run through eTravel, the merged immigration series and a private estimate, yields three totals and two growth rates.

SeaPRwire – On 4 September 2026, the Philippine Department of Tourism gave reporters a number: 4,115,860 international visitors for January to August, up 3.7% on the same months of 2025. On 18 September 2026 the department’s own dashboard displayed 4,415,860 for the identical period, up 0.78%. The distance between the two September 2026 releases is exactly 300,000 people, or 7.3% of the smaller figure. Neither release was withdrawn. Neither was labelled a correction.

For anyone outside the tourism trade this looks like a clerical problem. It is not. It is what happens when an official statistical series changes the instrument that produces it while keeping the name, the headline format and the political purpose. The country still received a quantity of foreign visitors between January and August 2026. Three separate counting systems were pointed at that quantity, and they returned three different answers.

This piece treats the three systems as instruments and runs the same task through each one. The task is simple enough to repeat: count every person admitted to the Philippines between 1 January and 31 August 2026 who is not a resident, break the total down by country of passport, and compare it with the same count for 2025. What follows is the output of each instrument, the arithmetic that separates them, and a short guide to which counter is fit for which job.

One task, stated so that it can be repeated

Precision about the task matters, because most of the disagreement in Philippine arrival statistics comes from people using the same words for different operations.

The unit is a person, not a trip. A visitor who enters twice in eight months counts twice, which is how almost every tourism authority in the world counts. The territory is the customs and immigration boundary, including airports and seaports. The window is 1 January to 31 August 2026, the period DOT reports as the year to date. The classification key is country of passport, which is what produces the familiar table of source markets.

The task has one property that makes it unusually hard to do cleanly. The Philippines has a very large diaspora, and a large share of the people crossing its border on a foreign passport are former citizens coming home to visit family. Under the Balikbayan programme, dating from Republic Act 6768 and amended by Republic Act 9174, a former Filipino who has naturalised abroad can enter visa free for a year. That person is a foreign passport holder on arrival and a returning family member in every other sense. Whether they enter the count decides whether the American market is 818,318 or 926,575.

DOT’s published total for 2025 was 6.44 million visitors, with tourism receipts of PHP 694 billion and tourism direct gross value added of PHP 2.27 trillion, or 8.1% of GDP. In 2025 the sector supported 7.7 million jobs. Those are the numbers the department is accountable for. The arrival counter is the input that feeds them.

Instrument one: a form filled in before landing

The first instrument is eTravel, the government’s online arrival registration. It is mandatory for every inbound traveller, including Filipino passport holders and crew, and it opens 72 hours before departure. A completed form produces a QR code that airlines check at check-in and immigration officers scan on arrival.

Because eTravel is a registration system, its raw output is a count of registrations, not a count of admissions. Almost everyone who registers does land, so the two numbers are close. They are not identical. A registration can be filed and the flight missed; a connecting passenger can be rebooked; a seafarer can register for a leg that is later cancelled.

The 4 September release used eTravel alone. Its market table read: United States 818,318, South Korea 727,379, Japan 350,191, China 310,088, Australia 234,156, Canada 231,972, Taiwan 154,957, United Kingdom 132,370, Singapore 126,812, India 77,883. In the January to August 2026 window, growth was led by China at 69.15% and India at 32.20%, with South Korea down 17.42% and Taiwan up 9.63%.

Instrument two: the form plus the immigration record

The second instrument merges eTravel registrations with records held by the Bureau of Immigration, the agency that actually admits people at the port. DOT launched a public dashboard on 16 September 2026 that runs on this merged basis, and the 18 September coverage described the source plainly: eTravel records from the Department of Information and Communications Technology, plus Bureau of Immigration records.

The merged total for the same eight months is 4,415,860, against 4,381,585 in 2025, a gain of 34,275 people. The market table rearranges itself. In the September 2026 release the United States rises to 926,575, or 20.98% of the total. South Korea sits at 744,732 in the same table, or 16.86%. Japan appears at 321,545, or 7.3%.

Table 1: Three published counts of the same eight-month task, with each publisher’s own stated change

Instrument Publisher and date Jan to Aug 2026 Change as published
eTravel registrations only DOT, 4 September 2026 4,115,860 +3.7%
eTravel plus immigration records DOT dashboard, 18 September 2026 4,415,860 +0.78%
Private estimate LPC, reported 7 October 2026 about 4.40 million roughly flat


Source: DOT 🔗, Philippine Tourism Data Dashboard, September 2026 (site home); Economic Daily News 🔗, 4 September 2026; Migrant Times 🔗, 19 September 2026

Instrument three: a number with no published method

The third instrument is a private estimate. On 7 October 2026, Chinese-language Philippine coverage cited LPC, a property research house, putting arrivals for January to August at about 4.40 million, essentially flat on 4.38 million a year earlier. The same report said growth peaked at 12% in February 2026, stalled from April, and turned negative year on year from May. For January to August 2026 it put China at about 303,000, up roughly 93%, and Korea at 744,000, down 22%.

The LPC number is worth including precisely because it is not an official series. It reaches the same order of magnitude as the merged count through a different route, and its market detail agrees with the merged series on Korea while agreeing with the eTravel series on nothing else. But no methodology is published: not the sample, not the treatment of balikbayan, not whether the count is by port of entry or by first destination. A number without a published method is a signal rather than a measurement, and it should be cited as one.

The 300,000 gap does not behave like an addition

The obvious explanation for the gap is that the merged series adds returning overseas Filipinos to the eTravel count. Three hundred thousand extra people over eight months, in a country with ten million citizens abroad, is a plausible size for that flow. The explanation is probably right in aggregate and wrong in detail.

If the merged series were eTravel plus an extra population, no market could shrink when you move from one to the other. Japan shrinks. The eTravel series has Japan at 350,191; the merged series has it at 321,545, a fall of 28,646, or 8.2%. China also falls, from 310,088 to 303,000, down 2.3%. The United States rises by 108,257, or 13.2%. Korea rises by 17,353, or 2.4%.

A series that is a strict superset cannot subtract 28,646 Japanese visitors. Something else is happening. The two instruments are not nested; they are differently shaped. A registration form records the passport and itinerary declared before travel. An immigration record reflects what the officer admitted, under which category, at which port. Reclassify a group, deduplicate a set of records, or change how a transit passenger is booked, and individual markets move in both directions while the total still rises.

That is the useful finding here, and it is more interesting than the headline gap. The 300,000 is not a pile of extra people sitting on top of the first count. It is the net of additions and subtractions across a much larger set of records, which means the market-level numbers from the two series cannot be mixed. A sentence that pairs the merged total with the eTravel country table is not approximately right. It describes a population that no instrument measured.

Four pairings, four growth rates

The growth rate is where the instrument choice becomes politically visible, because 2026 is the year the Philippines is trying to defend a target.

DOT’s stated goal for 2026 is between 6.4 million and 6.8 million international visitors, with 7 million described in September coverage as a stretch figure. Against a 2025 outcome of 6.44 million, the low end of that range is flat and the high end is a 5.6% gain.

Now count the ways to compute a year-on-year change for the first eight months. The eTravel series compares like with like and reports +3.7%. The merged series compares like with like and reports +0.78%. Cross the two and the answer changes sign.

Table 2: The same eight months, four ways of pairing a numerator with a baseline

Numerator Baseline Implied change
4,115,860 (eTravel, 2026) 3,969,000 (eTravel, 2025, implied) +3.7% as published
4,415,860 (merged, 2026) 4,381,585 (merged, 2025) +0.78% as published
4,115,860 (eTravel, 2026) 4,381,585 (merged, 2025) -6.1%
4,415,860 (merged, 2026) 3,969,000 (eTravel, 2025, implied) +11.3%


Source: derived from the three series in Table 1; the 2025 eTravel baseline is implied by dividing 4,115,860 by 1.037 and is therefore an estimate, not a published figure

The third row is the one that should worry the department. If a reader takes the newer 2025 baseline and the older 2026 numerator, Philippine arrivals fall 6.1% in the first eight months. If a reader takes the older baseline and the newer numerator, they rise 11.3%. The two published figures are both defensible. The two unpublished combinations are both nonsense, and both are one careless citation away from print.

The 2025 baseline moved by roughly 412,000 people between the two releases, which is larger than the 300,000 gap in 2026. That restatement is the part nobody has explained in public. A statistical office restating a baseline by 9.4% in 2026 is entitled to do so, but it normally publishes a note saying what changed. Without that note, the 2025 comparison set is a moving floor.

What each counter is good for

None of this makes any of the three instruments wrong. It makes them specialised. The mistake is treating them as interchangeable, and the fix is a short routing table.

  • For a headline about foreign tourists, use the eTravel series. It excludes most returning citizens by construction, which is what the word tourist is usually meant to capture.
  • For airline capacity, airport slots and hotel pipeline planning, use the merged series. It includes every admission, including the balikbayan who occupies a seat and a room.
  • For tourism receipts and GDP contribution, use neither. Use the Philippine Statistics Authority’s tourism direct gross value added and DOT’s receipts series, which count spending rather than heads.
  • For the 6.4 million target, ask which series the target is measured on. The published target does not say, and the two candidates differ by 7.3% at the eight-month mark.

That last gap matters arithmetically. To reach 6.4 million on the eTravel basis, the Philippines needs about 2.28 million arrivals in September to December, or 571,000 a month. On the merged basis it needs about 1.98 million, or 496,000 a month. The four-month run rate implied by the merged series is already close to the lower threshold; on the eTravel series it is not.

The 6.4 million target is a fourth instrument

A target is not a measurement, but it behaves like one once it enters a press conference. The 2026 target carries a complication: it was set before either the eTravel or the merged series existed in its current form, so the baseline it was built on is neither.

DOT’s own mid-year communications show the strain. On 6 October 2026 the tourism secretary was reported expressing confidence in the 6.4 million goal, with cumulative growth of 3.46% to that date. That 3.46% figure, reported in October 2026, is consistent with the eTravel series and inconsistent with the merged one. By 18 September 2026 the dashboard series showed growth of 0.78% for eight months. Both statements are true of their own instrument. Only one of them can be true of the target, and the target does not specify which.

There is a second complication, which is the China market. The Philippines opened 14-day visa-free entry for Chinese citizens in January 2026 at Manila and Cebu, and DOT has been seeking to extend it to Clark, Caticlan, Bohol and Palawan. Chinese arrivals rose from 1.74 million in 2019 to a peak that has never been recovered, then collapsed, and are now 310,088 on the eTravel basis for eight months of 2026, up 69.15% year on year. The October 2026 LPC estimate puts the gain at 93%.

A market growing at 69% or 93% from a small base is exactly where instrument differences bite hardest, because the base is small and the reclassification is large. If the visa-free expansion proceeds, the 2027 comparison will be built on a 2026 base that two instruments disagree about by 7,000 people in one market and 300,000 in total.

Receipts are the counter nobody argues about

Amid three arrival counters there is one number that has not been restated: money.

Tourism receipts for 2025 were PHP 694 billion. Tourism direct gross value added was PHP 2.27 trillion, or 8.1% of GDP, with shopping, accommodation and food services the largest components. Those figures come from the Philippine Statistics Authority’s tourism satellite account, which is built from expenditure surveys and business records rather than from a form filled in at the airport.

Dividing receipts by arrivals gives a rough yield per visitor. For 2025, on 6.44 million arrivals, PHP 694 billion works out to about PHP 107,800 per visitor, or roughly USD 1,900 at an exchange rate near 57 pesos to the dollar. That is a high figure by regional standards and it is one reason the arrival count matters less than it appears: a 300,000-person disagreement moves receipts by about PHP 32 billion, or 4.6%, if the marginal visitor spends the average. It does not move the GDP contribution, because the satellite account does not divide by an arrival count.

The distinction is worth holding on to. Arrival counters are an input to marketing and aviation planning. Receipts and value added are the economic output. When the two disagree, the output number is the one that has been through an accounting process.

What would settle this

Three things would close the gap, and all three are cheap.

First, publish the bridge. DOT has both series. A one-page table showing, for each source market, the eTravel count, the immigration count and the difference, would explain the 300,000 in an afternoon and end the guessing. Statistical agencies do this routinely when they change a collection method; the silence is a choice, not a constraint.

Second, restate 2025 on both bases and say so. The 2025 figure moved by about 412,000 between releases. Publishing both baselines, with the date each was computed, would let analysts compute a like-for-like change without inferring one.

Third, state which series the 6.4 million target is measured on. This costs nothing and removes an entire genre of misleading coverage, including the genre that quotes a merged total next to an eTravel market table.

Until then, the honest way to cite Philippine arrivals in 2026 is to name the instrument in the same sentence as the number. “4.4 million on the merged series” and “4.1 million on eTravel” are both accurate. “4.4 million visitors, with 818,318 Americans” is not, and it will keep appearing in print because the two numbers are one search apart.

Data basis

Data as of October 2026. The primary metric is international visitor arrivals for 1 January to 31 August 2026, as published by DOT in two releases and by LPC through Philippine media. All three totals are taken as published. The two crossed pairings in Table 2 divide one published numerator by another series’ baseline, which is arithmetic, not measurement.

Three definitions govern the work. The numerator counts persons, not trips. The growth denominator is the same eight calendar months of 2025. Markets are classified by passport, which is why the balikbayan treatment moves the United States line far more than the China line. One adjustment is deliberately not made: no returning-citizen flow is added or subtracted, because no publisher discloses it by market.

Limitations

  • The LPC estimate is triangulation only; no sample, method or port coverage is published.
  • The 2025 eTravel baseline is derived from a rounded 3.7% growth rate, so it carries about plus or minus 15,000.
  • Receipts per visitor divides spending by an arrival count from another collection system, so it is an average, not a marginal yield.

Sources


This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services.

About Global Infinity Labs

Global Infinity  Labs is an AI innovation company specializing in MCP data services.

Email: support@globalinfinitylabs.com


source https://newsroom.seaprwire.com/press-releases/technologies/philippine-tourism-has-three-arrival-counters-and-a-300000-gap/
10/28/2026

The $0.15 Bug Fix: Why Cognitum One’s MetaHarness Is the Most Dangerous Thing to Happen to Frontier Model Pricing

By: Alex Mercer – SeaPRwire – Reuven Cohen just did the one thing foundation model labs cannot answer. He made the model irrelevant to the bill. MetaHarness shipped this week alongside GitHub Universe 2026. It is an open-source factory for agent harnesses. You point it at a repository. It spits out a branded harness you […]

source https://newsroom.seaprwire.com/press-releases/technologies/the-0-15-bug-fix-why-cognitum-ones-metaharness-is-the-most-dangerous-thing-to-happen-to-frontier-model-pricing/

10/27/2026

Four Arabic AI Models on Three UAE Tasks: Where the Benchmarks Stop

Jais, Falcon-H1 Arabic, K2 Think and Copilot, run against three Abu Dhabi government workflows and against the Arabic benchmarks that have to stand in for them By: Robert Sterling – AsiaPresswire – The task is a trade licence renewal. A Dubai distributor wants to add two activities to an existing licence, and the application arrives […]

source https://newsroom.seaprwire.com/press-releases/finance/four-arabic-ai-models-on-three-uae-tasks-where-the-benchmarks-stop/

10/26/2026

Qatar’s Solar Target Is 30% of Capacity. The Energy Share Will Be Half That.

A myth-by-myth audit of the 4,000 MW solar plan, the 142 mtpa North Field build-out and the contracts that decide which number moves the grid By: Robert Sterling – AsiaPresswire – Drive west out of Doha on the Dukhan road and the landscape does one thing for about forty minutes: nothing. Then, near the Al […]

source https://newsroom.seaprwire.com/press-releases/finance/qatars-solar-target-is-30-of-capacity-the-energy-share-will-be-half-that/

10/25/2026

Micro-Dramas After 1 September 2026 — How China (Mainland) Rewrote the Rules

The three-tier licence regime, the AI labelling mandate and the compliance cost facing studios serving 664 million viewers By: Christian Brooks – AsiaPresswire – China (Mainland) counts 664 million micro-drama viewers, 59.0% of its 1.125 billion internet users, according to the China Internet Network Information Center’s 57th statistical report. It counts 814 million livestreaming users, […]

source https://newsroom.seaprwire.com/press-releases/finance/micro-dramas-after-1-september-2026-how-china-mainland-rewrote-the-rules/

Kiwi Ears Just Quietly Fixed What Most Hybrid IEMs Still Get Wrong

By: TechVanguard – SeaPRwire – Most hybrid IEMs still treat the midrange like an afterthought. Kiwi Ears just stopped doing that. The KE4 II keeps the four-driver count but completely reworks how the load is shared. That single change matters more than any new marketing slogan. The official story is clean. A 10mm biocellulose dynamic […]

source https://newsroom.seaprwire.com/press-releases/technologies/kiwi-ears-just-quietly-fixed-what-most-hybrid-iems-still-get-wrong/

10/24/2026

You Can Own a Philippine Hospital Outright — the Doctors Are Another Matter

A build-and-licence sequence for foreign capital, with the costs that are published, the ones that are not, and the order that keeps you out of a stranded asset. By: Robert Sterling – SeaPRwire – Foreign capital can hold the whole equity of a Philippine hospital. It cannot hold a stethoscope. That asymmetry decides more projects […]

source https://newsroom.seaprwire.com/press-releases/finance/you-can-own-a-philippine-hospital-outright-the-doctors-are-another-matter/

Inside the Tank: CORIS Puts the Alert Where the Sample Actually Sits

By: James Vance – SeaPRwire – Round-the-clock lab runs leave freezers and LN2 tanks unattended for hours. One missed temperature swing can wipe out years of material. CORIS is bringing the sensor inside the cabinet and the alert to the phone before the loss becomes permanent. That is the pitch at Future Labs Live next […]

source https://newsroom.seaprwire.com/press-releases/technologies/inside-the-tank-coris-puts-the-alert-where-the-sample-actually-sits/

10/23/2026

Thailand’s Tightrope: US Tariffs, Digital Ambition, and a Cooling Property Market in 2026

How Bangkok’s 21.9% Office Vacancy Meets 12.5% US Tariffs and a 2.3% Growth Forecast in 2026 By: Logan Pierce – SeaPRwire – Thailand in 2026 is a country caught in a vise. From Washington, a 12.5% Section 301 tariff sits on its exports like a permanent surcharge. From within, a digital economy transformation agenda promises […]

source https://newsroom.seaprwire.com/press-releases/finance/thailands-tightrope-us-tariffs-digital-ambition-and-a-cooling-property-market-in-2026/

10/22/2026

NFT Wallets Are Not Wallets: The Unsexy Engineering That Decides Who Owns the Internet’s Digital Stuff

By: Alex Mercer – SeaPRwire – Most NFT wallets are broken in a way their users never see. Not hacked. Not drained. Just quietly incomplete. A wallet that shows a JPEG and a token ID is a gallery, not custody infrastructure. The hard part was never display. It was metadata, standards, and the ugly business […]

source https://newsroom.seaprwire.com/press-releases/technologies/nft-wallets-are-not-wallets-the-unsexy-engineering-that-decides-who-owns-the-internets-digital-stuff/

10/21/2026

China’s Network Got 9.1% Busier. The Money Moved 0.7%.

A hydrant in Chengdu has a SIM card

By: Robert Sterling – SeaPRwire – Somewhere in Chengdu there is a fire hydrant that reports for duty every morning. It sends a short packet through a carrier’s network, several times a day, saying in effect that it is still a hydrant, still upright, still where the map says it is. The electricity meter in the same stairwell does something similar. So does the lift, the shared bicycle locked to the rack outside, and the parcel locker by the gate that has started charging tenants for the fourth hour of storage.

None of these objects has a voice plan. None of them streams video. Each of them holds a SIM card and each of them counts, in the regulator’s arithmetic, as a connection.

By the end of 2025 the three carriers in China (Mainland) — China Telecom, China Mobile and China Unicom — reported 2.888 billion cellular IoT terminal users, a net increase of 232 million over the year. That figure now exceeds the 1.061 billion mobile phone users on the same networks. Machines outnumber people on the Chinese mobile network by something close to three to one, and the ratio is still widening. IoT connections make up 61.3% of every terminal connected to those mobile networks.

This is the part of the story that never makes the press conference. The other part does: 5G base stations, gigabit fibre, computing hubs in the interior. Both parts are true, and they are true in the same year, and only one of them moves revenue.

The 9.1% and the 0.7%

Here are the two numbers the Ministry of Industry and Information Technology put at the top of its 2025 telecommunications statistics bulletin, released in late January 2026.

Telecommunications service volume — a quantity index, roughly a measure of how much traffic and how many connections the system carried, weighted and deflated — rose 9.1% year on year.

Telecommunications service revenue rose 0.7%.

Read those two lines next to each other for a while. Nine point one against zero point seven. A network that carried almost a tenth more of everything it carries, and brought in well under one percent more money for doing it. (The carriers will point out, reasonably, that volume and revenue measure different things, and that a deflated volume index is not a price. It is still a fairly stark pair of numbers to publish about yourself.)

This gap is not a Chinese peculiarity. Every operator in every market that built out fibre and 5G in the 2020s is living inside some version of it. What is distinctive about China (Mainland) is the scale at which the gap is now running, and the frankness with which the regulator puts both figures in the same bulletin.

The practical consequence lands on the capital side. If traffic grows at high single digits and revenue grows at a rounding error, then the return on the next base station is not the return on the last one. The engineering answer has been to chase cost out of the network. The commercial answer, so far, has been to sell connectivity in units nobody would have recognised as a product in 2015: a hydrant check-in, a lift diagnostic, thirty seconds of video from a dashcam.

Where the base stations sit

The build-out did not slow down. At the end of 2025 the country had 12.87 million mobile base stations in total, up 227,000 on the year. The split inside that number is more interesting than the total.

  • 5G base stations: 4.838 million, a net addition of 588,000, now 6% of all mobile base stations, up four percentage points on the year.
  • 4G base stations: 7.192 million, up only 80,000. 4G is still the larger single technology by site count, and it will be for a while.
  • Base stations with 5G RedCap capability: 2.064 million, equal to 7% of all 5G sites.

That last line is the one that explains the hydrant. RedCap — Reduced Capability, the industry’s own name for the cut-down version of 5G — is designed for devices that need more than a legacy IoT chip and far less than a phone. Lower bandwidth, lower power, cheaper modules, no need for the full antenna count. Rolling it out across 42.7% of the 5G estate within roughly a year of it becoming a deployment priority is the carrier’s direct answer to the margin question: if the network is going to carry 2.888 billion things, then a large share of those things should occupy the cheapest possible slice of it.

On the user side, 1.204 billion 5G mobile subscribers were counted at the end of 2025, 65.9% of all mobile phone users, up 9.2 percentage points in twelve months. The migration is far enough along that the remaining 34% is now the harder half: older devices, price-sensitive users, rural households whose 4G handset still does everything they ask of it.

RedCap, the cheaper 5G

It is worth slowing down on RedCap, because it is the clearest example of how the Chinese network shifted from a consumer build to an industrial one.

A full 5G module in a sensor is absurd. You do not need multi-gigabit downlink to tell a district heating utility that a valve is closed. What you do need is a module cheap enough to deploy in tens of millions, a battery that lasts years rather than days, and a network that will still be maintained in 2035. RedCap trades bandwidth and latency headroom for exactly those three things.

The numbers on the ground are straightforward. Out of 4.838 million 5G base stations, 2.064 million had been upgraded to accept RedCap devices by the end of 2025. That is not a pilot. That is a coverage decision made at national scale, and it is what makes the 28.88 million-per-year growth in IoT connections physically possible rather than aspirational.

  • Meters, hydrants, lifts and shared mobility: cheap modules, tiny payloads, years of battery life.
  • Dashcams and in-vehicle units: intermittent bursts, moderate bandwidth, high device counts.
  • Wearables and health monitors: low duty cycle, long replacement cycles, tight power budgets.
  • Factory sensors and inspection cameras: the segment that actually justifies 5G’s latency claims.

The fourth category is the one the policy documents care about, and the one that is hardest to count. The first three are the ones that show up in the connection statistics, and they show up in enormous numbers.

Fibre, 10G PON, and 74.99 million kilometres of glass

Fixed infrastructure kept the same rhythm. During 2025, 2.113 million kilometres of new optical cable were laid, taking the national total to 74.99 million kilometres. For scale, the equator is about 40,000 kilometres, so the country now has enough glass in the ground to circle it roughly 1,875 times. (This is the kind of fact that appears in every national telecom bulletin and means very little, which is precisely why it appears in every national telecom bulletin.)

The useful numbers sit under it:

  • Fixed broadband access ports: 1.251 billion, up 48.77 million.
  • Fibre access (FTTH/O) ports: 1.21 billion, up 50.30 million, now 8% of all broadband ports.
  • 10G PON ports capable of gigabit service: 31.62 million, up 3.419 million.
  • Fixed broadband subscribers: 691 million, up 20.99 million.
  • Subscribers on 1000 Mbps or faster: 238 million, up 31.57 million, 5% of all fixed broadband users.

Copper is functionally finished as an access technology. At 96.8% fibre ports, the remaining 3.2% is legacy estate being retired rather than a competing platform.

The gigabit number deserves a second look. Thirty-one point six million 10G PON ports serve 238 million gigabit subscribers, which is a ratio of roughly 7.5 subscribers per port — a reasonable split ratio for passive optical networking, and one that suggests the port build is running slightly ahead of subscriber demand rather than desperately behind it. Growth of 31.57 million gigabit subscribers in a year, against 20.99 million total broadband subscriber growth, means the gigabit tier is now where essentially all fixed broadband growth happens. People are not joining; they are upgrading.

Eight hubs, five of them in the west

The computing side is where national policy became physical concrete. The “East Data, West Computing” programme, known in Chinese as dongshu xisuan, was designed to move data processing away from the coastal provinces that generate it and toward the interior provinces that have cheap land and, more importantly, cheap electricity.

Eight national computing hub nodes were designated. Five of them are in the western region. The logic is not subtle: a training cluster or a cold-storage archive does not need to sit next to its users, it needs power that costs less and does not brown out in August, and land that a coastal municipality would rather use for something with a higher tax yield.

By mid-2025, the National Data Administration was reporting total computing capacity as second in the world by scale, alongside a claim about the geographic distribution that matters more than the ranking: interior nodes were taking a growing share of new capacity, and the coastal provinces were, for the first time, not the default answer to “where does this data centre go”.

Across the three carriers, 938,000 data centre racks were in service and offered externally at the end of 2025, up 108,000 on the year. That is a growth rate of about 13% in rack count, in a year when service revenue grew 0.7%. The description in the ministry’s own bulletin is revealing: the carriers’ focus has shifted from “broad coverage” to “deep integration”, from selling basic cloud resources to selling scheduling, and from building racks to making the racks they already have work together.

That shift is a margin story. Racks are capital. Scheduling is software. If you can sell the same rack twice by filling its idle hours, you do not need to build as many racks.

Racks, power, and the bill that arrives later

There is a cost to all of this that the connection statistics do not capture.

A 938,000-rack estate draws a great deal of electricity, and in China (Mainland) it draws it from a grid that is simultaneously absorbing an enormous build-out of solar and wind. The interior hubs were sited for cheap power, but “cheap power” in a province that is also industrialising fast is a moving target. Several western hub sites have already had to plan substation capacity alongside rack capacity, which is the sort of detail that turns a two-year project into a four-year one.

The second cost is the one that arrives later: depreciation. A base station built in 2020 is on a different depreciation clock from a RedCap upgrade installed on it in 2025, and a rack commissioned in a hub in 2023 is competing with racks commissioned in 2025 that are denser, better cooled and cheaper to run. The carriers’ capital budgets have to absorb both, and the revenue line grows at 0.7% while they do it.

  • Network traffic and connections: up sharply, and the volume index says 9.1%.
  • Revenue per unit of traffic: down, and the revenue line says 0.7%.
  • Capital intensity: still high, because coverage commitments do not expire.
  • Power and land: the input cost that the western hubs were supposed to solve, and partly have.

Put those four together and you get the actual strategic problem of Chinese telecom in the late 2020s. It is not a coverage problem and it is not a technology problem. It is the problem of an industry that has built something extremely good and has not yet found a way to charge for it in proportion to how good it is.

The west connected faster than the east

One regional detail in the bulletin deserves more attention than it got.

Gigabit subscriber penetration at the end of 2025, by region:

  • Western region: 36.1% of fixed broadband users, up 4.4 percentage points.
  • Eastern region: 34.6%, up 3.4 points.
  • Central region: 33.9%, up 2.7 points.
  • North-east region: 29.0%, up 5.4 points.

The west leads the east on gigabit penetration, and gained faster. There is a mundane explanation: the western provinces were starting from a lower base, and new build is cheaper to do at gigabit than upgrading an estate that already has copper-era plant in it. There is also a policy explanation, which is that the same programme that put five of eight computing hubs in the west has been pushing fibre and transmission spending there for several years.

Revenue, though, has not followed capacity eastward. Telecom service revenue share by region in 2025: eastern 50.9%, western 24.3%, central 19.7%, north-east 5.1%. The Yangtze River Delta on its own accounts for 23.2% of national telecom revenue; the Beijing-Tianjin-Hebei region, 9.1%.

So the network that is being built fastest is, in relative terms, being built where the money is thinner. That is a defensible national policy and a difficult commercial one, and the tension between the two is not going to resolve on its own.

Who pays for a network that keeps getting cheaper

Follow the money and the answer is: industry, mostly, and increasingly industry that is not telecom.

The 5G applications that show up in the ministry’s framing are industrial — connected factories, port automation, mining, grid inspection, and the “5G + industrial internet” category that has been in every five-year document since 2019. These are the applications that justify the latency and the slicing, and they are also the applications that require someone other than a carrier to do the integration work.

That is where the revenue shows up, if it shows up at all: not in the access charge, but in the system integration contract, the platform fee, the maintenance agreement. The carriers have spent a decade becoming very good at building networks and are now trying to become credible at selling everything wrapped around them, which is a different business with different margins and different competitors.

For the consumer side, the picture is simpler and less comfortable. Prices have fallen, speeds have risen, and 65.9% of mobile users are on 5G. Almost none of those users is paying a premium for it. The upgrade was absorbed into existing plans, which is exactly what the 9.1%-versus-0.7% pair describes from the other end.

1.19 billion HarmonyOS devices and 60% of AI patents

Two more figures from the same August 2025 State Council briefing are worth holding carefully, because both are large and both need a definition attached.

The first: the HarmonyOS ecosystem passed 1.19 billion devices, spanning more than 1,200 product categories — phones, cars, appliances, and a long tail of things that used to ship with a proprietary little operating system nobody updated. That is a genuine installed base, and it is the largest single piece of evidence that the country has an alternative client platform with real scale.

The second: 60% of the world’s artificial intelligence patents. This one is more slippery. Patent counts depend entirely on which office you count, whether you count applications or grants, and whether a family counts once or once per jurisdiction. Sixty percent of global AI patent filings is a defensible statement about filing behaviour at the national office. It is not a statement about who has the best models, and the briefing did not claim it was.

The reason both numbers belong in an article about telecom infrastructure is the same reason RedCap belongs in it. The build-out was never only about access. The stated goal, repeated across four years of policy documents, has been a domestic stack: domestic chips, domestic operating systems, domestic models, running on domestic networks, sold to domestic industry.

  • Access layer: 4.838 million 5G sites, 1.21 billion fibre ports, 31.62 million 10G PON ports.
  • Device layer: 1.19 billion HarmonyOS endpoints, 1.204 billion 5G subscribers.
  • Compute layer: eight national hubs, five in the west, 938,000 external racks.
  • Application layer: 2.888 billion IoT connections, 61.3% of everything attached to the mobile network.

Each layer is measured by a different agency, in different units, on a different schedule. That is precisely why the revenue figure is the one worth watching — it is the only number in the stack that cannot be flattered by choosing a unit.

What the bulletin declines to break out

A national statistics bulletin is a political document as well as a technical one, and its silences are informative.

There is no breakdown of IoT revenue per connection. There is no average revenue per user for the gigabit tier, only subscriber counts and port counts. There is no utilisation rate for the 938,000 racks, which is the single number that would tell you whether the western hubs are filling or standing half empty. There is no figure for how much of the 588,000 net new 5G sites were built to meet a coverage obligation rather than a demand signal.

None of these omissions is sinister. All of them are commercially sensitive, and a regulator that published them would hear about it. But a reader trying to work out whether the 9.1% versus 0.7% gap is narrowing or widening cannot do it from this bulletin alone, because the two lines that would settle it — revenue per IoT connection, and rack utilisation by hub — are exactly the two that are missing.

That leaves outside observers doing arithmetic on the numbers that are published. Divide 232 million net new IoT connections into the difference between total service revenue growth and what subscriber growth alone would explain, and you get a number with an enormous error bar and the right sign. It suggests IoT is being sold at a fraction of the per-unit revenue of a phone line, which is unsurprising, and that the fraction is not improving quickly, which matters.

Read the revenue line, not the press release

If you want to know how this goes, do not read the base station count.

Base stations are a commitment, and commitments get met. Racks are a commitment too. What is not a commitment is the revenue line, and that is where the honest information lives. Watch three things next year: whether service revenue growth climbs back above two percent, whether IoT connection growth continues to outrun any plausible growth in IoT revenue per connection, and whether the western hubs start reporting utilisation figures rather than capacity figures.

The hydrant in Chengdu will keep checking in either way. It has no opinion about any of this, which is of course the entire point of it.


source https://newsroom.seaprwire.com/press-releases/finance/chinas-network-got-9-1-busier-the-money-moved-0-7/